

Macro Snapshot
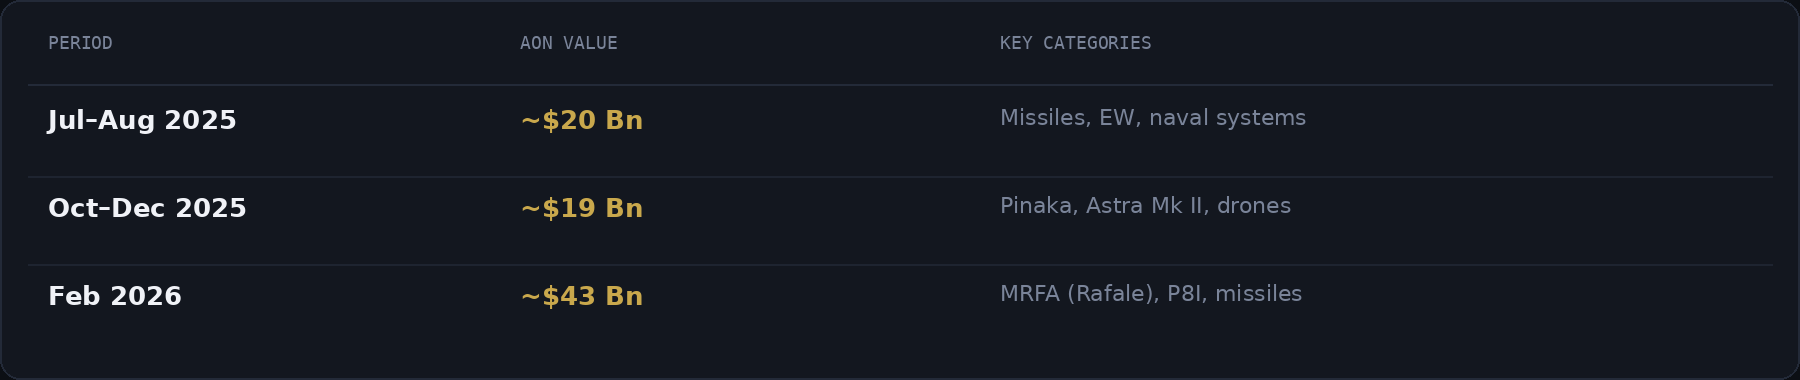
The FY26-27 defence budget stands at ~$93 billion — ~15% of the Union Budget and ~2% of GDP. [1] Capital outlay hit ~$26 billion (+21.8% YoY), with 75% earmarked for domestic procurement. [1] During FY26, DAC accorded AoN worth $39–43 billion — nearly 2x annual capital outlay — creating multi-year order visibility. [1]
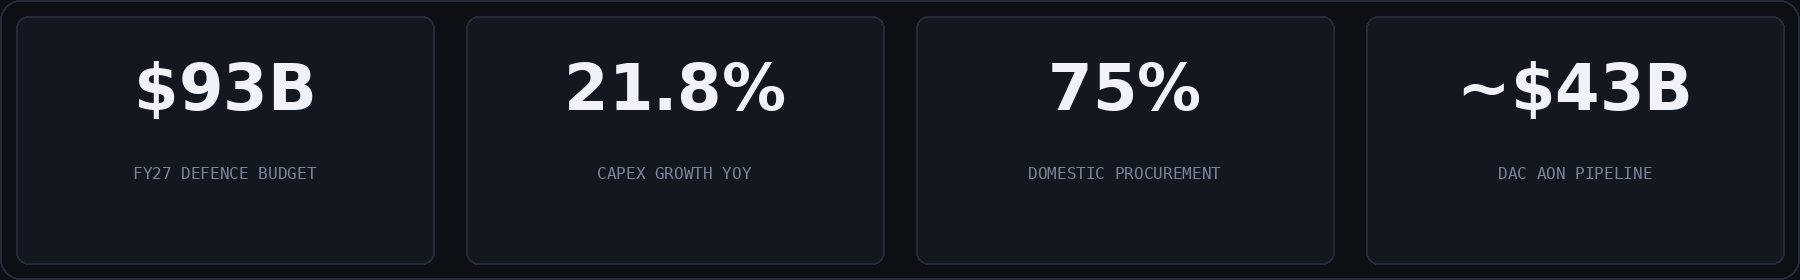
Defence exports crossed $2.8 billion in FY25 (34x growth over 11 years). Target: $6 billion by FY29. BrahMos to the Philippines ($375M), Akash and Pinaka to Armenia, India at DSA 2026 in Kuala Lumpur. [1] [5]
- THIS MONTH’S INSIGHT
The Series B Cliff & the New War Paradigm
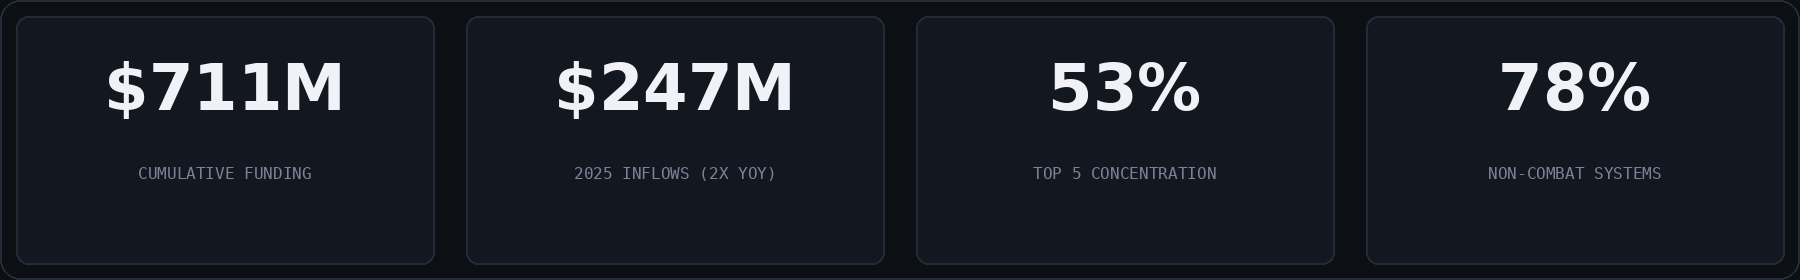
India’s defence tech ecosystem has crossed $711M in cumulative VC funding. In 2025, $247M flowed in — nearly double the prior year. [2] [3] The macro looks like a boom. But at the startup level, a structural fault line is widening: defence-only startups cannot raise follow-on capital from generalist VCs.
We call it the Series B Cliff. Most Indian defence startups derive 100% of their revenue from government contracts — iDEX grants, MoD procurement, PSU supply chains — with 2-5 year conversion cycles and unpredictable payment timelines. Growth-stage VCs need scalable, repeatable revenue. The government procurement narrative doesn’t translate.
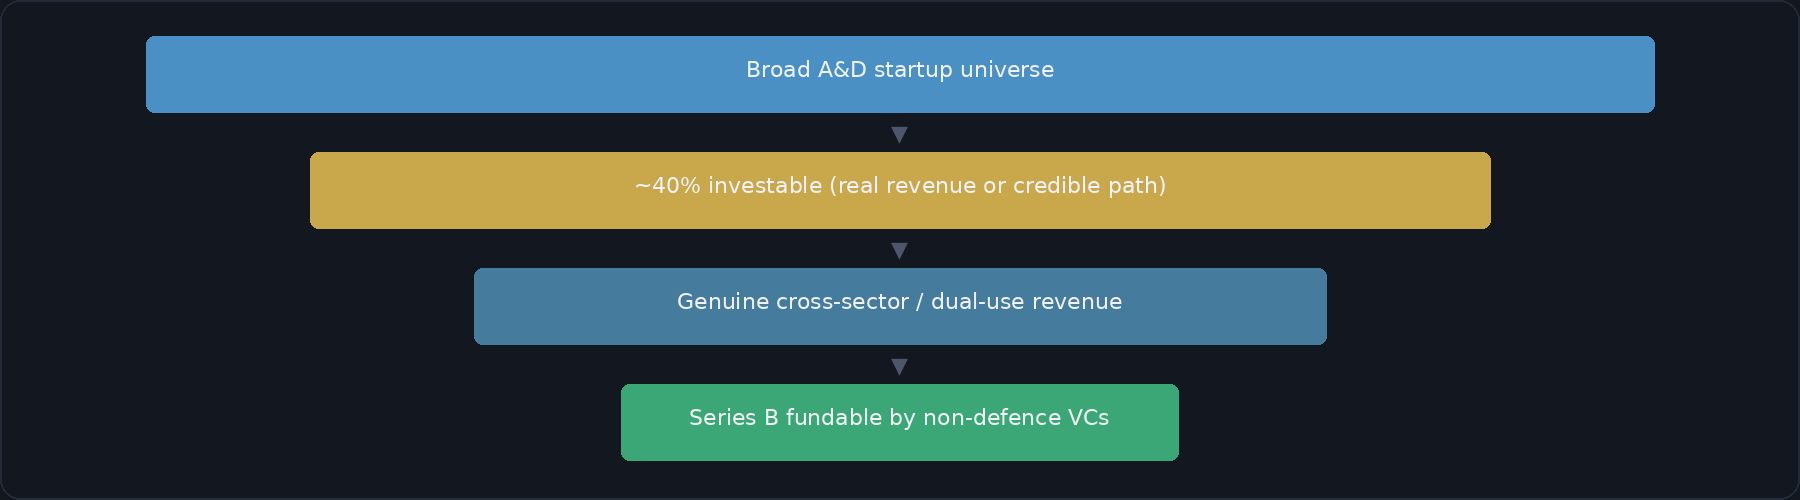
Companies that crossed the cliff share a pattern: Skyroot ($99.8M, Temasek/GIC), Pixxel ($95M, Google/NASA), Agnikul ($50M, 3D-printed engine), JJG Aero ($30M, Norwest, NADCAP-certified for Collins/Safran/Boeing), Constelli ($20M, General Catalyst, $3.9M revenue + exports). [12] Every one has commercial dual-use revenue, institutional certifications, international customers, or all three.
Companies that haven’t share a different pattern: “dual-use” in the pitch deck, single-use in the P&L. The gap between a “dual-use” slide and actual dual-channel revenue is where most startups will stall.
WHY THIS MATTERS NOW: Per Tracxn, the top 5 companies absorbed ~53% of all defence funding, and a single $100M+ Series B accounted for 40%+ of 2025 inflows. [2] Capital is pre-selecting 3–5 platform anchors. For everyone else, the runway to the cliff is getting shorter.
The second variable is war paradigm alignment. Recent conflicts have rewritten procurement priorities globally. The dominant capabilities now are cheap precision drones, autonomous swarms, EW, and counter-drone systems. Demand is shifting to integrated systems: drones, EW suites, AI-driven ISR, precision munitions, and C4ISR networks. [1] This shift structurally favours India — but only for companies building what’s being procured today.
The investor filter: genuine cross-sector revenue AND war-paradigm alignment. That intersection is narrow. Those companies cross the cliff. The rest need defence-specialist permanent capital.
India - Policy & Programmes
$3.6B+ Medium Transport Aircraft Programme — 60% Indigenous Content
DAC’s March 2026 AoN for 60 MTA to replace the An-32 fleet. 80% domestic manufacturing, 60% minimum indigenous content — mission computers, EW suites, SDRs. Directly pulls certified subsystem manufacturers into the prime contractor supply chain. [5] [6]
Three Independent Fighter Production Lines Post-2030
India will run three simultaneous fighter lines: AMCA led by a private player (Tata/L&T/Bharat Forge), Tejas MkII by HAL, and Rafales via Dassault-DRAL. First time a major combat aircraft programme is led by private industry. Creates a massive, diversified supply-chain ecosystem. [4]
GE & Safran Engine Deals Advance — Dual Propulsion Pathway for AMCA
GE confirmed (April 13) that critical ToT negotiations for a 110–130 kN engine are concluded. DRDO is co-developing a 120 kN engine with Safran using DMRL’s single-crystal metallurgy. Two engine tracks for one fighter — propulsion localisation at a scale India has never attempted. [5] [9]
Army Issues Requirement for Drone-Killer Air-to-Air Missile
The Army is seeking an IR-guided, fire-and-forget AAM for LCH Prachand and Rudra helicopters — 7 km range, 90%+ kill probability. Primarily a “drone-killer” after Mistral delays. Direct procurement signal for India’s counter-drone and missile startup ecosystem. [10]
Adani Defence Signs MoU with Leonardo — Helicopters, Electronics, Aerostructures
A watershed MoU covering helicopters, electronics, and aerostructures — part of the broader push to bring global OEM manufacturing into Indian private-sector facilities. Signals that Indian private players are now large enough to co-produce with European primes. [15]
- India A&D Startups
Defence Startup Funding Doubled to Record $247M in 2025
Highest annual inflow, nearly 2x 2024. A single $100M+ round (Raphe mPhibr) drove 40%+ of total. Non-combat systems took 78%. Bengaluru, Noida, Chennai account for 66%+. 116 VCs have participated to date. [2] [3]
Garuda Aerospace Files DRHP — First Major Drone IPO Push
Filed with SEBI in April 2026. Board approved raising ~$89M. ~$1.3M net profit on ~$4.9M revenue in H1 FY26. Valued at ~$250M. If this goes through, it creates the public-market exit pathway the drone ecosystem has been waiting for. [11]
Digantara Raises $50M Series B — Space Surveillance to Missile Defence
360 ONE, SBI Investment Japan, Peak XV, Kalaari. 15 satellite launches planned. $7–10M for US expansion. Total raised: $64.5M. The civilian-SSA-plus-military-early-warning model is exactly the dual-use positioning that crosses the Series B cliff. [8]
NewSpace Unveils Sheshnag-20 Swarming Loitering Munition
Bangalore-based NewSpace’s canister-launched, AI-guided swarm system — India’s first in its weight class. Unveiled at World Defence Show 2026 in Riyadh, now being presented to the Indian Army. [10]
SVAYATT-M1 Loyal Wingman — Private Startup vs HAL in the CCA Race
Paninian India (ex-DRDO/HAL founders) unveiled an AI-powered CCA with indigenous turbofan and stealth airframe. HAL advancing CATS Warrior in parallel. First time a private startup competes head-to-head with the state incumbent on a flagship combat programme. [10]
DIVYASTRA MK2 Strike UAV Begins Taxi Trials
Lucknow-based HoverIt: 1,500–2,000 km range, 8–12 hr endurance, 50–100 kg payload, 300–400 km/h terminal speed. GPS-denied, AI swarm capable. A private startup building a long-range autonomous strike platform. [10]
Nuvama PE Invests ~$24M in Val-Met Engineering
PE backing to expand aerospace manufacturing capabilities. Signals growing institutional capital flowing into India’s precision aerospace supply chain beyond pure-play startups — the manufacturing layer is getting funded too. [13]
BonV Aero Begins UAV Hub in Odisha
Work started on a UAV manufacturing hub for scale-up and skilling. The eVTOL/heavy-lift drone startup (Army Design Bureau top-10, IIT Mandi partnership) is building production infrastructure. [13]
Bengaluru Startup Developing India’s First Amphibious Drones
Founded by Nitte Meenakshi Institute of Technology alumni. Air-and-underwater capable — a novel cross-domain design. Applications: naval ISR, underwater inspection, search-and-rescue. Early stage, one to watch.
- Global News
Japan Fires World’s First Ship-Mounted Electromagnetic Railgun at Sea
Fired from JS Asuka. Projectiles at ~7x speed of sound, no explosives. The US spent billions and quit. Japan succeeded. Cheap shots, 100+ mile range, unlimited magazine. Japan is also completing its hypersonic glide vehicle three years ahead of schedule. [16]
Laser Counter-Drone Weapons Go Mainstream
AeroVironment unveiled the LOCUST X3 (20–30 kW laser C-UAS) in March. Israel’s Iron Beam is combat-deployed. UK ordered MBDA’s DragonFire ($430M, delivery 2027). Australia’s EOS Apollo can destroy 200 drones on a single charge. Each shot costs ~$13. [14] [15]
EU’s €1.5B Defence R&D Programme for 2026
€125M for next-gen MBT systems, €100M for hypersonic interceptors, €90M for semi-autonomous naval vessels, €20–30M for loyal wingman turbofan engines. A quarter of funding goes to future tech: quantum networks, AI, and drone swarms. [17]
NATO Restocking Cycle Creates Export Openings for India
Depleted inventories and supply-chain diversification are pushing NATO nations beyond traditional Western OEMs. India is increasingly competitive in ammunition, radars, EW systems, and subsystems. [1]
- Conclusion
The macro is structural: $93 billion budget, 75% domestic procurement, $43 billion in DAC pipeline, and three independent fighter lines post-2030. But the startup ecosystem faces the Series B cliff — defence-only revenue doesn’t raise growth capital. The companies that will survive are the ones with genuine dual-use revenue, institutional certifications, and alignment with what’s being procured today. The opportunity is enormous. The filter is narrow.
One Number to Remember
53%
The share of all Indian defence tech VC funding absorbed by just the top 5 companies. Capital isn't dispersing across the ecosystem — it's concentrating into a handful of platform bets. If your startup isn't in that group, the clock on your runway just got louder.
References
Kotak MF — Defence in India: Policy, Power, and a New Industrial Growth Cycle (Mar 2026) — kotakmf.com/Information/blogs/india-defence-sector-growth
Tracxn — India Defence Tech Report 2026 (Jan 2026) — tracxn.com/report-releases/india-defence-tech-report-2026
Business Standard — Defence startup funding doubles to $247M (Jan 2026) — business-standard.com
IDRW — Three Independent Fighter Production Lines Post-2030 (Apr 2026) — idrw.org
IDRW — F414 Engine Deal & MTA Indigenous Content (Apr 2026) — idrw.org
IDRW — Medium Transport Aircraft 60% Indigenous Content Mandate — idrw.org
Aerospace Global News — AMCA stealth intake design (Mar 2026) — aerospaceglobalnews.com
TechCrunch — Digantara raises $50M (Dec 2025) — techcrunch.com
Newsd — AMCA 120 kN engine with Safran & DMRL (Mar 2026) — defence.newsd.in
Defence.in — Ghatak UCAV, Army AAM, INS Aridhaman, NewSpace, Paninian, HoverIt — defence.in
Inc42 — Garuda Aerospace DRHP / IPO Tracker 2026 — inc42.com
LAFFAZ — India Startup Funding Feb 2026 (JJG Aero, Constelli) — laffaz.com
Manufacturing Today India — Nuvama/Val-Met, BonV Aero (Apr 2026) — manufacturingtodayindia.com
Breaking Defense — AeroVironment LOCUST X3 (Mar 2026) — breakingdefense.com
Al Jazeera / IADB — Laser C-UAS Weapons; Adani-Leonardo MoU — aljazeera.com / iadb.in
DSEI Japan — Japan Emerging Technology Leader (Railgun, Hypersonics) — dsei-japan.com
Defense News — EU Defence Fund 2026 Work Programme (Dec 2025) — defensenews.com
Pivotal Vectors is published monthly by Pivotal Research | www.pivotalresearch.in | satish@pivotalresearch.in
Data sourced from publicly available reports. Figures represent reported or estimated values at time of publication. Not investment advice.